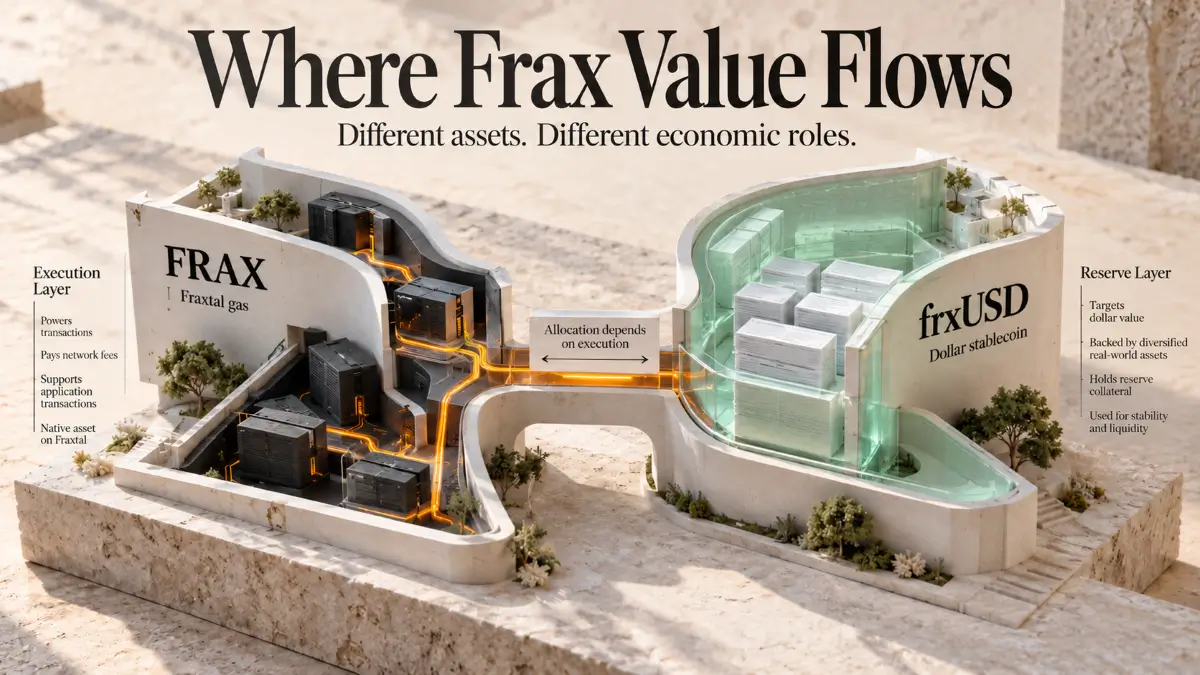
Stablecoin growth can benefit users, liquidity providers and an issuer without delivering the same benefit to its ecosystem token. Frax makes that distinction especially important. It combines decentralized finance products, stablecoin infrastructure and the Fraxtal execution network, but their financial benefits follow different routes. This Frax Review examines how the FRAX token connects to those products, where the connection remains conditional and why older descriptions of its supply now require care.
FRAX now pays transaction fees on Fraxtal, while frxUSD serves as the dollar stablecoin. Governance has also approved changes to supply policy and revenue allocation, although older documentation still describes previous rules. Understanding the project means following the money through that changing structure and evaluating the stablecoin, gas asset and savings products separately.
Disclaimer
Research and education are the purpose of this article. It does not provide investment, trading, staking, legal or technical audit advice. FRAX carries market and liquidity risks, while Frax products introduce additional dependencies involving smart contracts, custody, redemption and infrastructure. Product terms and deployed implementations may change.
Disclosure
Research draws on public Frax documentation, governance records, exchange notices, market-data services and published security assessments checked on October 18, 2026. Project statements reflect intended or reported mechanisms and do not, by themselves, establish live performance. This review does not claim firsthand product testing, an independent code audit or a complete reconciliation of native and bridged token supply.
Quick Verdict
Frax has working financial products and an identifiable use for FRAX as Fraxtal gas. Its stablecoin integrations also extend beyond its own chain. Those facts support the product case, but they do not establish an automatic transfer of stablecoin success to token holders.
The central question concerns execution. Approved monetary policy differs from older token documentation, reserve income has several competing destinations and governance participation requires separate locking arrangements. Stronger conclusions need current supply reconciliation, implemented revenue-routing records and evidence that customers continue using the products without excessive incentives. Frax merits analysis as an operating financial system, with each asset and dependency assessed on its own terms.
Key Takeaways
Which Frax Asset Does What?
| Asset or Product | Main Function | Economic Distinction |
|---|---|---|
| FRAX | Native transaction-fee asset on Fraxtal | Market-priced token, separate from dollar reserves |
| frxUSD | Reserve-backed dollar stablecoin | Redemption and reserve quality matter |
| sfrxUSD | Yield-bearing vault exposure to frxUSD | Strategy income and vault risks differ from FRAX ownership |
| frxETH and sfrxETH | Ether representation and staking-yield vault | Ethereum staking economics, separate from FRAX rewards |
| veFRAX | Time-weighted ecosystem governance participation | Lock duration affects influence and flexibility |
| Fraxtal | Smart-contract execution network | Usage, fee collection and operational security need their own records |
Research takeaway: Similar names do not create identical rights. Product analysis starts with the asset someone actually holds and the mechanism that gives it value.
FXS Became FRAX Through Different Migration Routes
Official documentation dates the one-to-one upgrade from Ethereum FXS to native Fraxtal FRAX to April 28, 2025. Binance subsequently announced its own January 2026 conversion process. These events belong to the same transition, but they do not establish one universal migration date for every wallet and exchange.
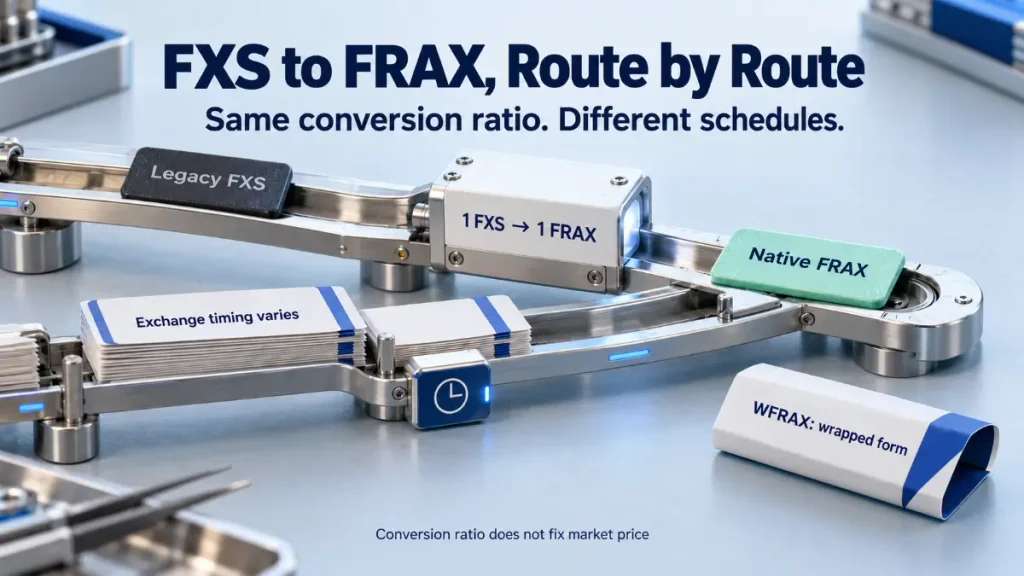
Native FRAX also differs from an ERC-20 representation. Fraxtal users can wrap it as WFRAX for contract compatibility, while crosschain routes involve additional representations and transfer infrastructure. Ethereum’s familiar legacy FXS address therefore cannot serve as a universal identifier for every asset carrying the Frax name.
Migration preserves the conversion ratio under the relevant process. It does not guarantee an unchanged market price or identical withdrawal support. Network and contract identifiers remain more reliable than an exchange account label alone.
frxUSD Reserves Belong to a Different Asset
Frax began with a fractional-algorithmic stablecoin model, but current frxUSD documentation describes full collateralization through permitted cash-equivalent reserves. These include tokenized Treasury funds held through regulated custodians. Older records also refer to Legacy Frax Dollar, which previously used the FRAX name. That naming history makes the specific asset more important than its ticker alone. The current frxUSD reserve framework does not provide backing for the market-priced FRAX gas token.
Reserve quality and redemption access also answer different questions. Frax documents custodian contracts that exchange frxUSD against eligible reserve assets. Availability depends on the assets remaining in the relevant contracts, and underlying reserve tokens can carry access requirements. Full collateralization does not mean every wallet can obtain any selected reserve asset through an identical process.
For analysis, backing, reserve liquidity and practical redemption should remain separate checks. A reserve disclosure can support the backing claim while leaving operational questions about timing, eligibility and concentration. None of those disclosures establishes a dollar redemption right for FRAX itself. Confusing the two assets would misstate the token’s fundamental risk.
Fraxtal Runs on an OP Stack Architecture
Some token documentation calls Fraxtal a layer 1 network, while its dedicated architecture documentation describes an OP Stack modular layer 2. L2BEAT classifies the tracked system as an optimium. That classification reflects external data availability and additional trust assumptions, rather than the security model of a conventional Ethereum rollup publishing its transaction data on Ethereum.
Frax’s technical documentation describes custom data availability that stores chain data externally and posts a reference to Ethereum. Redundant storage can improve operational resilience, but storage copies alone do not establish permissionless verification or unrestricted withdrawal capability.
These distinctions matter more than the category label. Researchers need to identify who orders transactions, who submits state claims and what users can do if those operators fail. Running a node to follow the chain does not automatically grant the right to produce blocks or earn validator rewards. The token overview itself places additional validator functionality in a future hardfork.
Small Gas Balances Can Support Frequent Transactions
Paying for execution gives FRAX a direct use that a purely optional governance token lacks. Someone must fund the gas expenditure associated with transactions on Fraxtal, whether the user pays personally or an application sponsors the cost. That requirement establishes utility, but it does not determine how large a lasting token balance the network needs.
Low fees let a small working balance fund many transactions. Frequent activity can therefore coexist with modest aggregate gas inventory. Applications may also replenish balances only when necessary. Counting transactions without measuring actual fees and retained balances would exaggerate what the activity proves about demand.
For a stronger assessment, fee expenditure should accompany repeat-user activity and incentive costs. Researchers should also trace the destination of collected fees. Tokens moving into a treasury can return through spending, while permanently retired tokens follow a different supply path. Network usage becomes financially meaningful through those executed flows, not through transaction counts alone.
Consider a hypothetical application spending 100 FRAX on fees each month. Daily replenishment could let it operate with a much smaller balance than its monthly expenditure. Faster replenishment might support more activity without a proportional increase in inventory. This example describes token velocity, not measured Fraxtal usage. It explains why fee demand needs both a flow measure and a balance measure before anyone can infer lasting ownership demand.
ReserveLink Directs Income Toward Application Users
Frax’s June 2026 ReserveLink announcement describes routing part of frxUSD reserve yield into applications, including Aave. This can support lenders and stablecoin distribution without requiring every beneficiary to own FRAX. The feature addresses a practical issue: reserve assets can generate income even while the corresponding stablecoins sit inside a lending market.
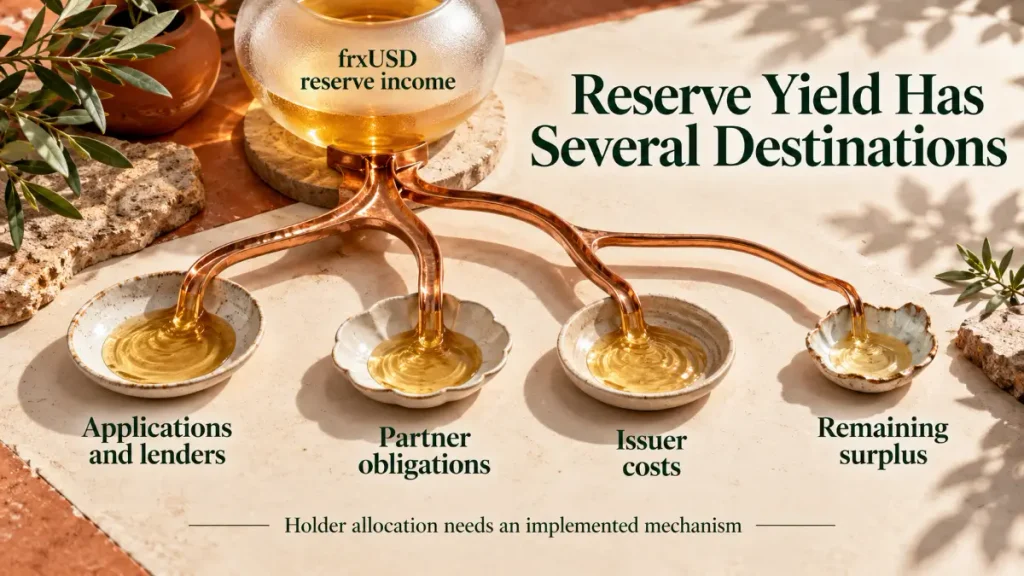
Sharing that income can make frxUSD more useful to integration partners. It can also create a cost of distribution for the issuer. Funds sent to application users cannot simultaneously count as the same funds retained for token-holder benefits.
Commercial success therefore needs more than a growing reserve balance. Analysis should follow gross reserve income through partner arrangements and operating expenses to the remaining surplus. Token analysis then asks whether an implemented mechanism directs part of that surplus toward eligible participants. Without that reconciliation, a productive reserve portfolio can create an overstated impression of holder income.
Suppose a hypothetical reporting period produces $100 of gross income. If partner obligations absorb $30 and issuer costs absorb another $20, only $50 remains before further allocations. Applying a holder-sharing percentage to the original $100 would overstate the relevant base. These figures are illustrative, not Frax financial results. Their purpose is to show why both the percentage and its denominator need disclosure.
Following Frax Income to Its Recipients
| Economic Activity | Immediate Beneficiary or Use | Further Proof Needed |
|---|---|---|
| Fraxtal execution | Network operation and fee collection | Persistent FRAX working balances and actual fee routing |
| frxUSD reserve income | Issuer, partners and approved recipients | Reconciled surplus after obligations and costs |
| Stablecoin liquidity programs | Market liquidity and participating users | Retention after incentives and sustainable unit economics |
| veFRAX participation | Voting influence and eligible distributions | Current eligibility, funding and completed transfers |
| Treasury deployment | Operations and ecosystem development | Measurable results relative to resources spent |
Research takeaway: Activity can support Frax without requiring proportional FRAX purchases. Each proposed benefit needs a documented route and observable execution.
Polygon Distribution Broadens frxUSD’s Reach
Polygon’s May 2026 announcement confirms live Curve foreign-exchange pools using frxUSD as the dollar pairing. Its October update describes a separate EURe/frxUSD pool on Uniswap v3 involving Monerium and Capa. These examples establish specific distribution routes. They do not quantify total demand or establish reliance across the wider financial system.
They also illustrate why stablecoin growth and gas-token demand can diverge. Activity on another network can expand frxUSD’s reach while paying transaction fees to that network’s gas asset. FRAX needs an additional economic connection to benefit directly.
An integration announcement establishes availability. Sustained customer use requires a time series covering repeat activity, liquidity, incentive spending and reliable exits. Incentivized deposits can be useful during market formation, but they do not establish durable demand on their own. The strongest record would show customers continuing to use the product after promotional support changes, with revenues sufficient to support the distribution arrangements that attracted them.
Liquidity also needs a practical test. Pool balances can look substantial while a trade in one direction faces poor execution. Researchers should examine spreads, available depth and redemption alternatives alongside aggregate deposits. Those measurements describe whether customers can actually use the announced route at a reasonable cost.
Savings Vaults and Ether Staking Have Different Income Sources
sfrxUSD gives exposure to a yield mechanism built around frxUSD. Its documentation describes strategy allocation across reserve-related income and other approved approaches. A quoted yield therefore requires an explanation of the strategy, costs and conditions, rather than an assumption that every return comes from identical underlying activity.
Frax Ether has another structure. Holding frxETH alone does not earn the documented staking yield. Depositing into sfrxETH provides vault exposure to rewards associated with Frax’s Ethereum validators. The distinction matters because a product called staking can refer to different assets, sources of income and withdrawal mechanics across the ecosystem.
Neither product establishes a universal yield for FRAX holders. Product revenue can strengthen the wider business, but benefits to the gas token depend on separate allocations and participation rules. Comparing advertised percentages without matching the underlying asset and risks would obscure those differences. Competitive yield today also does not establish a permanent advantage over other providers.
veFRAX Links Voting Weight to Lock Duration
The vote-escrowed FRAX documentation permits lock periods from one week to 208 weeks. Voting weight increases with the amount and duration committed, then declines toward the end of the lock. The balance is nontransferable under the documented structure.
This creates a clear participation mechanism. Someone seeking greater governance influence can commit FRAX for longer, reducing immediate flexibility. However, a lock does not itself generate external revenue. Any distribution needs an independent funding source, eligibility rules and a functioning claim or payment process.
Researchers should distinguish time commitments from permanent supply removal. Locked assets still exist, and their eventual availability belongs in supply analysis. Similarly, voting influence does not establish that a holder controls every operational decision. Concentration, delegation and the authority responsible for executing approved changes all affect the practical value of participation. Those conditions can change during a long lock even if its scheduled end date stays the same.
Tokenomics
FIP-441, a Frax Improvement Proposal, sets out a 143 million FRAX supply cap, a 43 million premint framework and finite annual spending budgets. It removes the earlier perpetual tail-emission plan. Frax’s February 2026 project update reports the proposal as passed. Approval establishes the policy decision, but this review does not independently verify every mint, deployment or enforcement mechanism implementing it.
| Supply Reference | Position Documented During This Review | Interpretation |
|---|---|---|
| Approved supply policy | 143 million FRAX under FIP-441 | Policy ceiling, separate from verified live issuance |
| Premint framework | 43 million FRAX across specified purposes | Requires implementation and treasury accounting |
| Circulating estimate | Approximately 93.63 million | Provider estimate, not a complete supply reconciliation |
| Reported total supply | Approximately 99.68 million on major aggregators | Does not resolve native-chain and policy differences |
| Maximum-supply fields | CoinMarketCap shows about 99.68 million, CoinGecko shows no finite maximum | Provider fields conflict with each other and approved policy |
| Older emission description | Initial 8% tapering toward 3% | Historical documentation, unsuitable as an unqualified current schedule |
Research takeaway: A single circulation percentage cannot summarize Frax’s supply position. Policy, minted supply, treasury ownership and provider classifications require reconciliation.
Reported Circulation Depends on What Counts as Supply
CoinMarketCap and CoinGecko both showed roughly 93.63 million circulating tokens during this check, alongside approximately 99.68 million total supply. Those figures suggest roughly 94% circulation relative to that reported total. They do not demonstrate that only a small amount can ever become available under every policy interpretation.
For illustration, dividing the same 93.63 million by a 143 million ceiling gives approximately 65.5%. This is a denominator comparison, not an unlock forecast or a claim that the remaining amount will reach markets on a particular date.
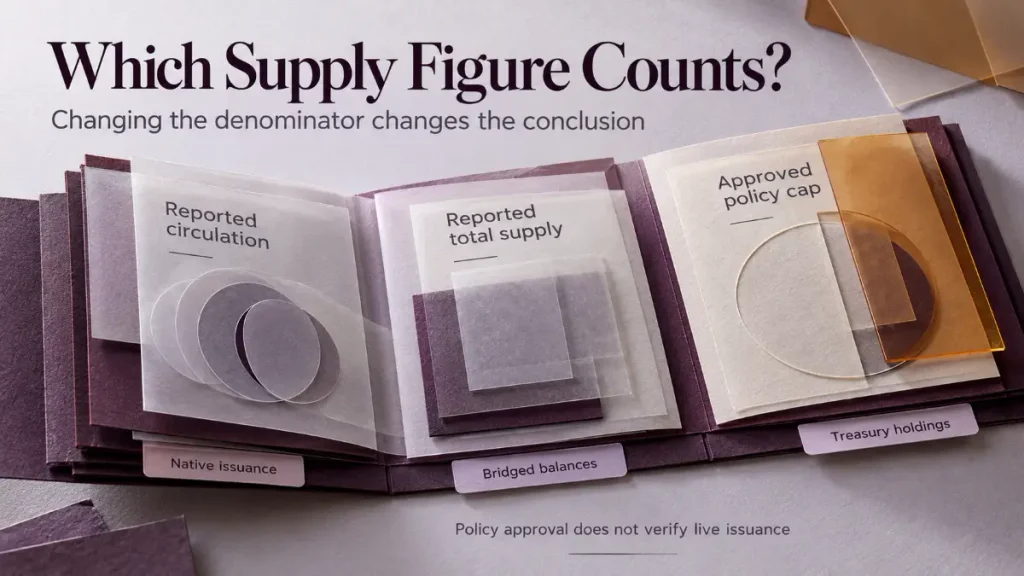
Complete accounting would identify native issuance, legacy tokens held in bridges, wrapped balances, treasury holdings and any implementation of approved allocations. Adding every representation together could double-count the same economic units. Conversely, reading only the legacy Ethereum contract could miss relevant native-chain changes. Supply analysis needs that reconciliation before assigning confident dilution percentages.
Treasury Budgets Still Need Spending Records
Approved spending authority tells researchers what the treasury may deploy. It does not establish that the full allowance has moved, that recipients have sold it or that spending produced useful results. Minting, transferring and selling belong to separate stages of the financial record.
The practical concern is how token-funded operations and incentives compare with the demand they create. A useful treasury report would connect authorizations with disbursements, recipient categories, remaining balances and outcomes. A fixed cap can still coexist with meaningful changes in tradable supply. Capital allocation within that boundary remains an operating decision that researchers need to assess.
Fee Recycling Changes the Burn Narrative
The token overview still describes a Frax Burn Engine receiving selected ecosystem fees. FIP-441 instead records stopping that mechanism and describes recycling fee flows through the revised revenue structure. This review therefore does not treat a permanent burn as an established consequence of every Fraxtal transaction.
Destruction reduces existing units, while treasury collection changes ownership and potential future spending. Either route needs transaction evidence. Even a verified burn would require comparison with issuance, distributions and previously restricted holdings returning to circulation. Counting gross burns alone would give an incomplete account.
veFRAX Revenue Sharing Faces a Reporting Test
FIP-441 describes up to 10% of eligible net protocol revenue for veFRAX, with periodic governance review. That wording does not promise 10% of gross reserve earnings or a fixed payment to every FRAX holder.
Follow-through deserves particular attention. A June 2026 revenue-share discussion on the governance forum questioned reporting and voting mechanics. Subsequent comments through October 1 asked about the expected vote. These comments show an unresolved public question in that thread, rather than proving that no relevant action occurred anywhere else.
The appropriate response is to seek dated reports, vote outcomes and completed distribution records. A policy can authorize a benefit while operational work determines whether eligible participants receive it. Readers need both parts before treating the arrangement as established income. Clear reporting should also explain what expenses and partner obligations reduce gross receipts before any eligible surplus reaches the distribution calculation.
Reporting consistency matters beyond a single payout. Regular periods, stable definitions and explanations of changes let readers compare results. A larger reported distribution has limited meaning if the eligible base, accounting period or payment asset changed at the same time. Governance transparency should make those differences visible without requiring holders to reconstruct them from scattered forum comments.
Frax Audits Cover Defined Upgrades and Code
Frax’s audit archive contains reviews of different products and upgrades. The March 2025 North Star report examined specified migration-related contracts and code versions. Its findings included two critical issues. The report states that the team addressed issues or acknowledged them as acceptable behavior. Historical findings do not establish that the same vulnerabilities remain exploitable today.
The July 2025 ChainSecurity assessment covered separate upgrades involving legacy-dollar bonds, sfrxUSD and related infrastructure. It identified low-severity issues with a mixture of corrections, specification changes and accepted risks. Its conclusions belong to that reviewed scope.
Security research should match a live deployment to the relevant implementation and report. An older review cannot certify every later upgrade, bridge route or reserve operation. Likewise, a market-data security score cannot replace assessment of permissions and dependencies. This review verifies the existence of substantive published assessments, but it does not claim complete audit coverage across the current ecosystem.
Fraxtal Operators and Bridges Add Trust Assumptions
L2BEAT’s Fraxtal assessment identifies reliance on permissioned state proposers, external data availability and upgrade authority without a user exit window. These are implementation-specific trust assumptions. They do not establish that an operator has acted improperly, but they identify conditions under which users rely on operational honesty and continuity.
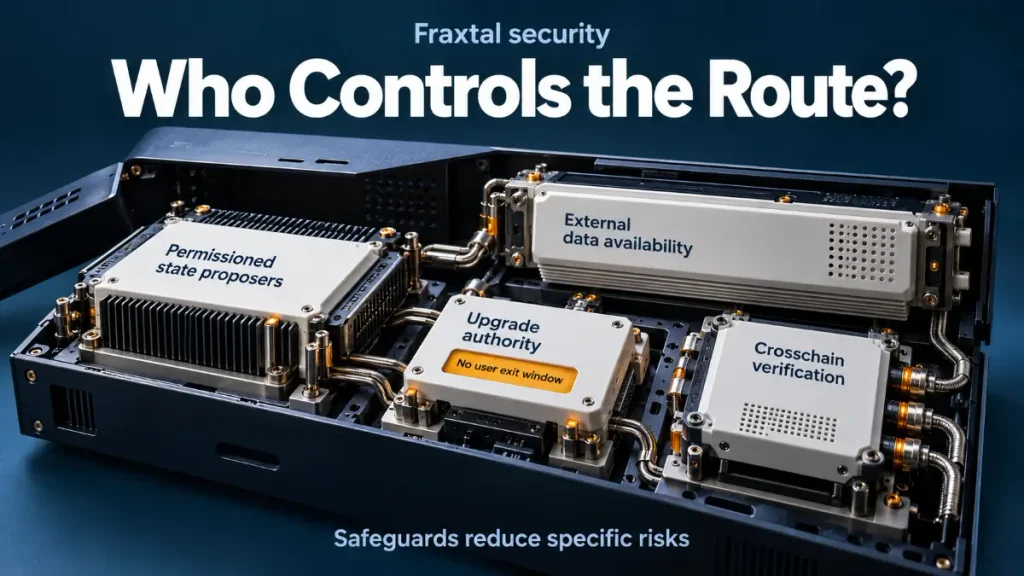
Frax separately describes hardware-backed signing, controlled operational access and crosschain verification arrangements. Such safeguards can reduce particular risks while leaving the underlying authority and dependency structure intact.
Crosschain assets introduce another layer. Frax’s transfer documentation describes multiple contract designs and verification settings. A route’s safety depends on its deployed configuration, authorized parties and destination contracts. A recognizable ticker cannot reveal those details. Reliability needs scrutiny across the full path from the source asset to the destination balance, including any process required to return or redeem it.
How Far the Available Evidence Supports FRAX
| Public Evidence | What It Supports | What It Cannot Establish Alone |
|---|---|---|
| Live gas payments | Functional network utility | Large or lasting FRAX inventories |
| Stablecoin integrations | Availability in external applications | Recurring customer demand or holder income |
| Reserve disclosures | Information about backing assets | Equal redemption access under all conditions |
| Governance approval | A recorded policy decision | Complete implementation or immutable enforcement |
| Audit reports | Review of specified code and versions | Universal current safety |
| Revenue distributions | Executed benefits for eligible recipients | A permanent entitlement or future return |
Research takeaway: The strongest assessment combines adoption records, reconciled finances and implementation evidence. None can substitute fully for the others.
Frax’s Commercial Case Starts With Useful Distribution
Frax combines a dollar asset, savings infrastructure, trading integrations and a network with native gas utility. That combination gives developers and financial applications several ways to use the system. Distribution through other networks also means its stablecoin business need not depend entirely on activity inside Fraxtal.
The commercial opportunity lies in reliable liquidity, integration and redemption. For FRAX, a stronger case would connect those advantages to retained gas balances, useful governance participation and transparent economic benefits. Scale and execution determine the significance of that connection.
Supply Reconciliation Would Sharpen the Holder Case
Three records would materially improve confidence. First, a current supply reconciliation should connect approved policy with native issuance, legacy representations and treasury holdings. Second, income reporting should bridge reserve earnings to costs, partner allocations and completed distributions. Third, usage data should show retention after incentives change.
Stronger contract verification would help independently of those financial records. Current deployment maps, upgrade disclosures and clear operator permissions would make the practical security model easier to assess.
The thesis would weaken if spending consistently outpaced durable adoption, reporting remained difficult to reconcile or holders relied on obsolete burn and emission descriptions. Market liquidity also matters separately from product quality. An operating protocol can still have thin token markets, concentrated liquidity or substantial volatility. Historical price declines establish risk, but they do not establish either a bargain or a recovery path.
Final Assessment
Frax’s most useful question is where customer activity reaches FRAX after every intermediary has taken its share. Gas utility provides a direct connection. Stablecoin growth creates a broader opportunity whose benefits depend on costs, distribution choices and governance execution.
This Frax Review finds a substantive product ecosystem alongside unresolved accounting and implementation questions. Approved supply policy deserves attention, but so do conflicting documentation and incomplete verification of its execution. Published audits add useful evidence without removing custody, bridge or operator dependencies.
The next meaningful improvement would be clearer records linking usage, revenue, supply and eligible holder benefits. That would make the token case easier to assess on its operating merits, with less reliance on branding, historical prices or assumptions about automatic value capture.
Key Questions About Frax and FRAX
Is FRAX the dollar stablecoin?
FRAX is the market-priced Fraxtal gas asset. frxUSD is the separate dollar stablecoin.
When did the FXS upgrade become available?
Official documentation dates the one-to-one upgrade to April 28, 2025. Exchanges followed their own conversion schedules.
Does every Frax product require FRAX gas?
No. Activity on other networks can use those networks’ gas assets, even when frxUSD participates.
Is the perpetual 3% emission model current policy?
Approved FIP-441 policy removes it. Older documentation still describes the previous model.
What maximum supply does approved policy specify?
FIP-441 specifies 143 million FRAX. Live implementation and conflicting market-data fields need separate verification.
Does high reported circulation remove supply risk?
No. The denominator, treasury holdings and actual deployment of approved allocations still matter.
Does holding frxETH earn staking yield automatically?
No. The documented staking-yield vault is sfrxETH, which has its own mechanics and dependencies.
Does veFRAX promise a fixed return?
No. Locking provides participation rights. Distributions depend on applicable rules, funding and execution.
Does every gas payment permanently burn FRAX?
This review does not establish that. Revised governance policy conflicts with the older burn description.
Do audits cover every current Frax risk?
No. Reports cover defined code and versions, while custody, operating authority and later changes require separate assessment.

Founder & Managing Editor of CryptosMedia. Zahid Hussain leads evidence-based crypto research covering tokenomics, security, governance, adoption, and risk.
CryptosMedia separates verified facts from interpretation, avoids buy/sell recommendations, and updates reviews when major evidence changes.
2 thoughts on “Frax Review: Where Stablecoin Growth Reaches FRAX”