
Enterprise demand is no longer Aethir’s weakest link. Its distributed GPU network has delivered billions of compute hours, supports hundreds of thousands of GPU Containers, and now serves large enterprise infrastructure contracts. Unlike many AI tokens, Aethir does not need future adoption to prove somebody wants its product.
This Aethir Review asks a harder question: can that demand create enough recurring ATH demand to absorb tokens entering circulation through vesting, Checker rewards, compute-provider incentives, and service settlement? Aethir can build a successful cloud business while ATH faces a tougher economic test because customers create compute demand as providers and network participants receive ATH.
Real Compute Demand Is Already Measurable
Aethir coordinates distributed GPU infrastructure for AI, gaming, and other compute-heavy applications. Cloud Hosts supply computing resources, Indexers connect workloads with suitable capacity, and Checker Nodes monitor whether Containers remain available and meet required performance standards. AI training, inference, and rendering run on provider hardware rather than inside blockchain consensus.
This makes Aethir different from intelligence markets such as the system discussed in our Bittensor review. Bittensor coordinates machine-intelligence markets; Aethir sells computing infrastructure and uses blockchain for incentives, settlement, staking, and verification around that service.
Current operating data gives that infrastructure real weight. Aethir’s live GPU dashboard shows roughly 434,400 GPU Containers across 94 countries and more than 2.35 billion delivered compute hours. Those figures prove operating scale, but they do not reveal utilization by GPU class, customer concentration, or operating margin.
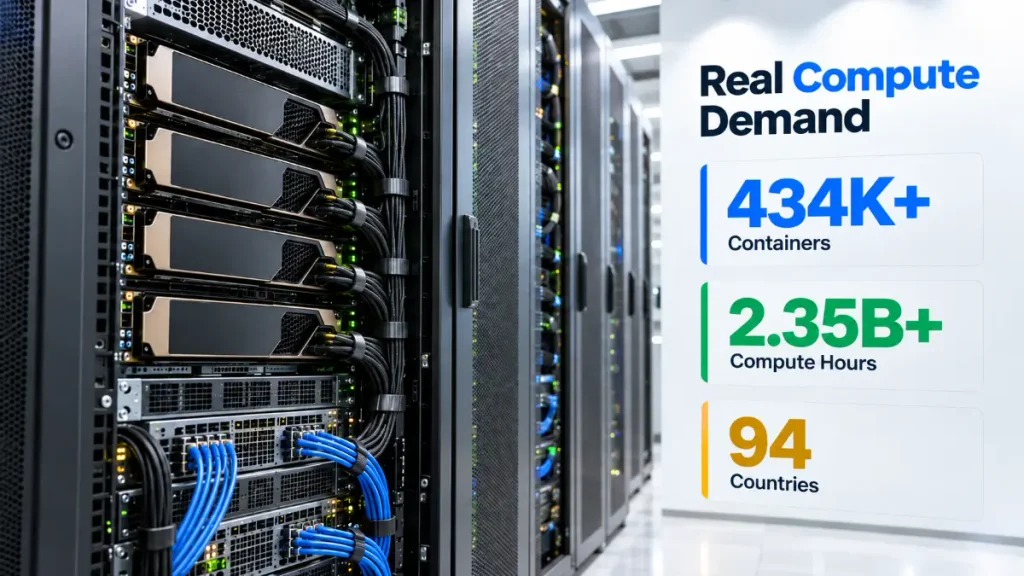
That distinction sets up the real token question. Aethir no longer needs to prove product demand exists; it needs to show that growing product demand strengthens ATH faster than ATH distribution expands.
Revenue Quality Matters More Than the Old $166M ARR Headline
Aethir’s historical revenue numbers look impressive, but dates matter. During Q3 2025, Aethir reported $39.86 million in quarterly network revenue and said annual recurring revenue had reached $166 million. Its 2025 year-end review later reported more than $127.8 million in network revenue for that year.
The current dashboard shows about $45.47 million in ARR and roughly $188.03 million in cumulative network revenue since June 2024. These figures measure different periods, so they do not automatically conflict. What remains missing is a clear public reconciliation explaining why the current recurring-revenue run rate sits far below the peak ARR reported in 2025.
Aethir has clearly generated substantial compute revenue. The evidence does not support carrying the old $166 million ARR figure into September 2026 as if it were still current.
| Evidence | What It Shows | What It Does Not Prove |
|---|---|---|
| ~$45.47M live ARR | Aethir still has meaningful recurring compute demand | Historical $166M ARR remains current |
| ~$188.03M cumulative network revenue | Paying activity has persisted since 2024 | $188.03M is annual revenue or profit |
| 2.35B+ delivered compute hours | Infrastructure has processed substantial workloads | Every GPU is highly utilized |
| ~434,400 GPU Containers | Aethir has broad available infrastructure | Every Container represents equal hardware value |
| $260M Axe agreement | Enterprise buyers are committing to large dedicated capacity | Aethir has already recognized $260M as revenue |
The table separates evidence from inference. Aethir’s operating case is strong, but each metric becomes misleading when it is stretched beyond what it actually measures.
The $260M Axe Deal Shows Contracted Demand, Not Current Revenue
Enterprise contracting may be Aethir’s strongest growth signal in 2026. Axe Compute signed a 36-month, $260 million take-or-pay agreement for a dedicated cluster of 2,304 NVIDIA B300 GPUs. A later update said the first $43 million payment under the agreement had landed and Aethir had begun provisioning infrastructure, with full deployment targeted for Q3 2026.
A take-or-pay agreement gives infrastructure providers better demand visibility than a purely short-term spot marketplace because the customer commits to capacity. Even so, Axe Compute and Aethir are separate entities. Contract value, customer prepayments, Axe revenue, and Aethir network revenue should not be merged into one number.
The deal still matters because it shows Aethir can participate in deployments measured in thousands of next-generation GPUs. The next test is how much contracted value becomes delivered compute, recurring network revenue, and ultimately ATH settlement.
This model also differs from the open provider-bidding system discussed in our Akash Network review. Aethir is moving toward longer-duration enterprise capacity commitments rather than relying only on marketplace-style demand.
ATH Settlement Creates Demand, but Not Permanent Scarcity
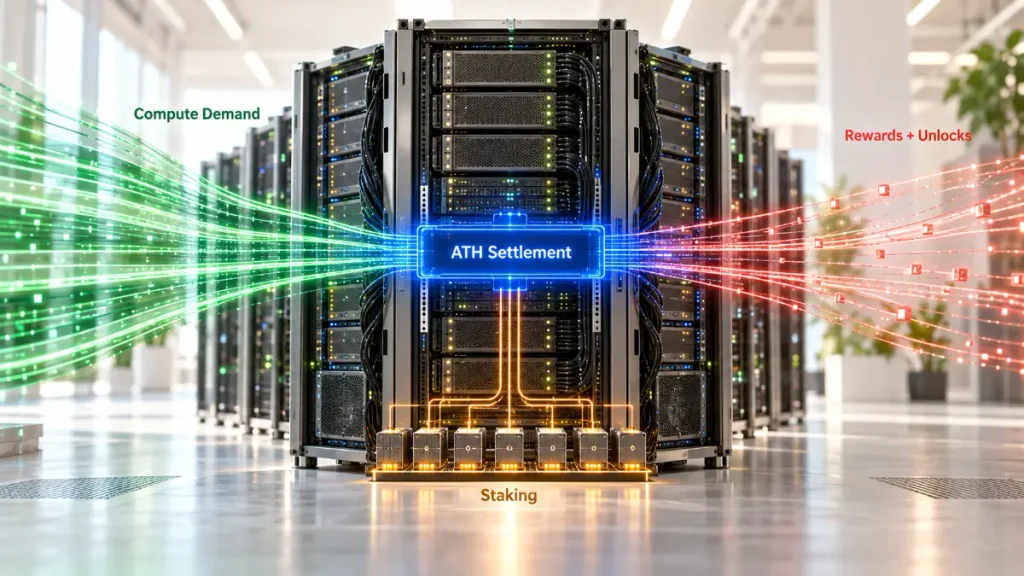
ATH has genuine transactional utility. Aethir can price Cloud service fees in fiat while settling payments with Cloud Hosts in ATH, so enterprise customers do not need to become token speculators before their spending reaches ATH settlement. This lets real cloud activity interact with the native token without forcing customers to manage token-price exposure directly.
Cloud Hosts also need ATH collateral. Relevant GPU operators must stake ATH while providing compute, and current Cloud Host documentation applies a 180-day unlock period after unstaking. That creates a temporary token lock tied directly to infrastructure participation rather than permanent scarcity.
Neither mechanism permanently removes ATH. Providers can eventually withdraw service fees, and stakers can later unlock collateral. Transactional and collateral demand therefore give ATH stronger utility than a decorative governance token, but they do not create permanent scarcity.
The dashboard also reports around 10.5 billion ATH in cumulative on-chain compute purchases and more than 9.67 billion ATH in total rewards distributed. These figures measure different flows and should not be subtracted from each other, but their scale reveals the central contest: Aethir generates substantial ATH-linked activity while also distributing substantial ATH incentives.
Capacity Rewards Pay for Readiness Before Utilization
Enterprise buyers expect capacity to exist before they need it. Aethir addresses that supply-side problem through Proof of Capacity, which rewards Cloud Hosts for keeping eligible Containers online and available, while Proof of Delivery rewards completed workloads. Aethir currently sets the network Utility Ratio at 0.5, giving equal weight to capacity and delivered work within the relevant reward calculation.
This design solves a real marketplace problem. Without readiness incentives, providers could remove expensive hardware whenever utilization falls, leaving the network unable to meet sudden enterprise demand. The token cost is that Proof of Capacity can distribute ATH before equivalent customer revenue exists.
A growing GPU fleet can therefore reflect two different forces: customer demand pulling more hardware onto the network, or rewards making available hardware profitable enough to stay online. Raw capacity does not show which force dominates.
This is a broader DePIN problem visible in our io.net review. Distributed compute networks often need subsidies to build supply before demand matures. A sustainable model emerges when paid utilization gradually carries more of provider economics.
Aethir Tokenomics: Utility Meets an Expanding Float
ATH has a stated maximum and total supply of 42 billion tokens, but the current circulating position is less clear across public sources. CoinMarketCap reports about 20.12 billion ATH circulating, while Aethir’s live dashboard shows roughly 23.31 billion ATH, matching its published September 2026 emissions schedule.
That leaves a material methodology gap between market-data circulation and Aethir’s own current figure. Maximum supply therefore explains only the lifetime ceiling; it does not tell readers how much ATH is scheduled, vested, claimable, staked, locked, or freely circulating at a given moment.
Team allocation follows an 18-month cliff and 36-month linear vesting period, while investor allocation follows a 12-month cliff and 24-month linear vesting period. Aethir also distributes Checker Node allocation over four years under performance rules, and compute providers receive rewards through Proof of Capacity and Proof of Delivery.
ATH has real demand-side functions through compute settlement, Cloud Host collateral, and broader staking activity. The tokenomics question is not whether ATH has utility; it is whether utility-linked demand can absorb tokens as they become economically available.
ATH Supply and Vesting Snapshot
| Tokenomics Area | Current Position | Why It Matters |
|---|---|---|
| Maximum supply | 42B ATH | Sets stated lifetime supply ceiling |
| CoinMarketCap circulating supply | ~20.12B ATH | Market-data circulation remains below Aethir’s current figure |
| Aethir dashboard circulation | ~23.31B ATH | Live network figure now matches the September schedule |
| September 2026 emissions schedule | ~23.31B ATH | Published release schedule agrees with the live dashboard |
| Team vesting | 18-month cliff + 36-month linear vest | Team allocation continues entering availability over several years |
| Investor vesting | 12-month cliff + 24-month linear vest | Investor distribution remains part of supply expansion |
| Checker rewards | Four-year performance-based release | Supports verification while distributing ATH |
| Compute rewards | Proof of Capacity + Proof of Delivery | Rewards both infrastructure readiness and actual work |
| Service-fee settlement | Fiat pricing, ATH settlement | Real customer spending can create transactional ATH demand |
| Cloud Host stake | ATH collateral required | Locks supply while participating hardware remains active |
| Core tokenomics test | Demand absorption vs distribution | Business growth must outrun vesting, rewards, and provider payouts |
One ATH Supply Gap Still Needs Reconciliation
As of September 10, 2026, Aethir’s live dashboard and its September emissions schedule both show 23,308,238,268 ATH. CoinMarketCap reports about 20.12 billion ATH circulating, leaving a gap of roughly 3.18 billion. That difference is too large to dismiss as rounding.
Several explanations could contribute. CoinMarketCap may apply a different circulation methodology, while claimability, vesting, treasury treatment, classification, and reporting timing can also affect what each source counts. Public material does not fully reconcile those methodologies.
Aethir’s live dashboard now agrees with its published September release schedule. The unresolved issue is therefore narrower but still material: why market-data circulation remains about 3.18 billion ATH below Aethir’s current figure.
Better transparency would separate scheduled, vested, unclaimed, staked, treasury-held, and freely circulating ATH in one place. Until then, dilution analysis should preserve the distinction rather than manufacture false precision.
Vesting Delays Liquidity, Not Distribution
Token emissions do not automatically become immediate market supply. Current Cloud Host documentation uses staged release for rewards: 30% can become claimable immediately, another 30% after 90 days, and the remaining 40% after 180 days. Service fees follow a separate waiting period, while staked ATH also has an exit process before withdrawal.
These delays reduce immediate liquidity from rewards, but they do not erase distribution. A vested reward still belongs to the recipient; a time lock changes when it can enter the market, not whether the network distributed it.
ATH analysis should therefore avoid two opposite mistakes. Treating every emitted token as immediate sell pressure exaggerates near-term risk, while ignoring vested rewards understates future supply. The better question is how much ATH moves from scheduled allocation to vested ownership, then to claimable balances and liquid circulation as compute-driven demand develops.
Revenue Must Replace Subsidy as Aethir Matures
Team and investor unlocks are obvious dilution sources, but Aethir also distributes ATH to operate the network. Checker Nodes need incentives to monitor infrastructure, Cloud Hosts need compensation for keeping expensive GPUs ready, and providers need payment for completed work. These rewards buy real services rather than serving as meaningless inflation.
The economic problem appears when token subsidies remain a large share of provider economics after customer demand should be mature enough to support more of the network directly.
- Healthy progression: ATH incentives attract hardware → paid utilization rises → service fees become more important → subsidy dependence falls.
- Weak progression: ATH rewards attract hardware → available capacity grows → utilization stays uneven → providers remain heavily dependent on emissions.
That distinction matters more than raw GPU count. Aethir can add more Containers without improving ATH economics if customer-funded workloads do not rise with them.
Checker Nodes Verify Service Quality, Not Economics
Checker Nodes solve a physical verification problem. Distributed infrastructure cannot rely only on a blockchain record saying hardware exists, so Aethir Checkers run liveness and quality checks to confirm that Containers remain available and meet expected standards. They repeatedly test Proof of Capacity conditions, while Proof of Delivery helps verify completed service.
A successful check does not prove a GPU is profitably utilized, a customer contract will renew, or provider rewards are sustainable. Checker monitoring also does not secure token or bridge contracts simply because the compute layer passes its quality tests.
Aethir therefore has several independent trust boundaries: provider hardware, Checker verification, Indexer routing, staking, token settlement, and cross-chain infrastructure. Evidence from one layer should not be treated as proof for another.
Bridge Security Is Separate From GPU Reliability
April 2026 showed why those boundaries matter. Aethir disclosed an exploit involving cross-chain ATH bridge adapter contracts. Unauthorized access enabled fraudulent ATH creation on affected alternative chains and released locked bridge liquidity from Ethereum-side infrastructure.
Aethir said the canonical 42 billion ATH supply on Ethereum remained intact and reported that the incident involved around 13.3 million ATH held by users on affected alternative chains. Aethir disconnected the compromised adapters and launched a compensation process.
The incident did not show that Aethir’s GPU cloud had failed; it exposed a separate cross-chain security surface. That distinction prevents two bad conclusions: dismissing the compute network because a bridge failed, or minimizing bridge risk because compute continued operating.
CertiK’s current Aethir page lists multiple contract-review entries and currently shows its audit workflow in remediation. That supports the existence of security review activity, but it does not provide a blanket guarantee for every Aethir contract, bridge adapter, or future integration. Audit scope matters as much as the audit label.
ACCELERATE Adds Physical Infrastructure Risk
Aethir’s ACCELERATE strategy moves the project deeper into physical infrastructure. The program has secured access to 10 data-center sites across the United States and Europe with up to 20 megawatts of planned capacity. Aethir projects up to $700 million in contracts by the end of 2026 and more than $2 billion in total contract value once all sites reach full development.
Those figures are forward targets, not realized revenue. Their importance lies in what they reveal about Aethir’s business model: distributed orchestration alone cannot create thousands of new B300-class GPUs in the right location when existing provider supply cannot satisfy contracted demand.
Large enterprise clusters also need power, cooling, networking, physical security, financing, and predictable deployment schedules. ACCELERATE can strengthen Aethir’s enterprise moat, but it also exposes the project to site development, power access, construction, GPU procurement, deployment delays, and greater capital intensity.
Aethir is becoming a hybrid infrastructure business that combines distributed compute coordination with enterprise contracting and increasingly direct capacity development. That differs from the job-oriented GPU economics discussed in our Render Network review. “Decentralized GPU cloud” remains accurate, but it no longer describes the whole economic system.
What Would Show Demand Is Outrunning Emissions?
ATH does not need emissions to fall to zero; it needs economic demand to grow faster relative to distribution. Several measurements would make that relationship easier to judge.
- Current ARR stabilizes and grows, with a clear reconciliation to the earlier $166 million peak.
- On-chain compute purchases grow faster than ATH reward distribution across meaningful periods.
- Paid utilization rises by GPU class, especially for expensive enterprise hardware.
- Cloud Host staking grows because providers need collateral for productive infrastructure, not only because rewards are attractive.
- Large contracts move from announced value into activated capacity, delivered compute, and network revenue.
- Aethir reconciles scheduled, vested, staked, claimable, and freely circulating ATH.
- Service fees support a larger share of provider economics as the network matures.
These metrics would answer the title question with evidence rather than narrative. A mature compute network should need less subsidy for each dollar of customer demand, not more.
Verdict: Enterprise Demand Is Real; Absorption Is Unproven
Aethir has already proved something many AI infrastructure tokens have not. Its network has paying activity, billions of delivered compute hours, substantial cumulative revenue, hundreds of thousands of Containers, and enterprise deployments involving next-generation NVIDIA hardware.
ATH also sits inside that business through service-fee settlement, Cloud Host staking, Checker incentives, and compute rewards. That connection is stronger than a governance token attached to an unrelated cloud business, but distribution remains the central weakness.
Team and investor vesting continue, Checker rewards distribute ATH, Proof of Capacity subsidizes ready hardware, Proof of Delivery rewards completed work, and providers eventually receive settlement they can withdraw. At the same time, CoinMarketCap’s circulation figure still sits materially below Aethir’s current dashboard and September schedule.
Enterprise demand can overcome those pressures only when contract value becomes live capacity, recurring service revenue, ATH settlement, and productive collateral demand. Current evidence proves demand is real; it does not yet prove demand absorbs distribution faster than ATH becomes economically available.
Aethir’s next test is therefore not another GPU-count milestone. It is whether compute-driven ATH demand grows faster than rewards, vesting, and provider payouts. If that happens, Aethir can align a real infrastructure business with stronger token economics. Until then, the cloud business and ATH token should be evaluated as connected systems, not assumed to be the same success story.
Frequently Asked Questions
Aethir is a distributed GPU cloud network that supplies computing infrastructure for AI, gaming, and other GPU-intensive workloads. Cloud Hosts provide hardware while Aethir coordinates resource allocation, verification, incentives, and settlement.
Yes. Aethir reports billions of delivered compute hours, substantial cumulative network revenue, and large enterprise capacity agreements. These figures support real usage, although contract value and cumulative revenue should not be confused with current recurring revenue.
Aethir reported $166 million ARR during Q3 2025, while its live dashboard now shows about $45.47 million. Public reporting does not provide a complete reconciliation explaining the difference, so the old peak should not be presented as current ARR.
ATH supports compute settlement, Cloud Host staking, network rewards, broader staking, and ecosystem participation. Relevant compute providers also lock ATH as collateral while operating infrastructure.
Public figures still differ by methodology. As of September 10, 2026, CoinMarketCap reports about 20.12 billion ATH circulating, while Aethir’s live dashboard shows roughly 23.31 billion ATH, matching its September 2026 emissions schedule. The remaining gap is about 3.18 billion ATH.
Aethir said the canonical 42 billion ATH supply on Ethereum remained intact. The incident involved cross-chain adapter infrastructure rather than core GPU compute.
The main risk is an absorption gap. ATH distributed through vesting, Checker incentives, compute rewards, and provider settlement may grow faster than transactional, staking, and collateral demand created by real compute usage.

Founder & Managing Editor of CryptosMedia. Zahid Hussain leads evidence-based crypto research covering tokenomics, security, governance, adoption, and risk.
CryptosMedia separates verified facts from interpretation, avoids buy/sell recommendations, and updates reviews when major evidence changes.
3 thoughts on “Aethir Review: Can Enterprise Demand Outrun ATH Emissions?”