
Towns Protocol already has something many token projects spend years trying to prove: a working product with paid onchain activity. Users can create programmable communication Spaces, sell memberships, send tips, and interact through encrypted messaging infrastructure. The harder question is whether that product activity creates enough durable demand for TOWNS.
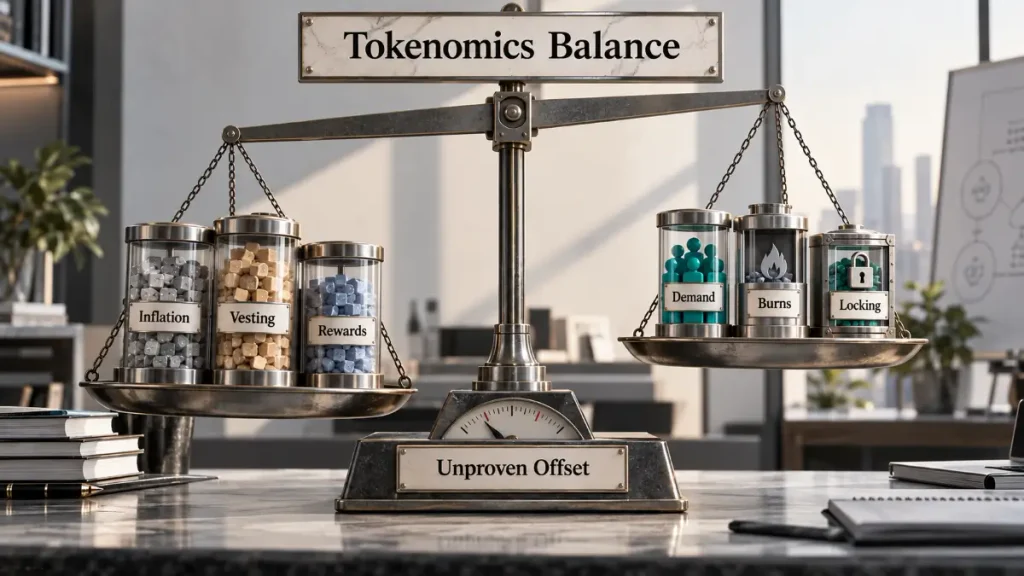
This Towns Protocol Review focuses on that economic bridge. TOWNS secures network participation, supports delegation and governance, and receives a potential value-capture route through fee-funded buybacks and burns. At the same time, the token has entered its post-launch inflation phase while large allocations move through vesting schedules. That means product growth alone is not enough. Buybacks, burns, staking, and organic demand need to absorb new supply at a meaningful scale.
The timing also matters because Binance added TOWNS to its Monitoring Tag on September 4, 2026. Binance did not identify one specific reason for the decision. The tag should therefore be treated as an exchange-level risk signal, not proof that inflation, vesting, or buybacks caused the review.
This article is for research and education only. It does not provide financial advice or a buy or sell recommendation. Supply data, staking rules, governance decisions, and exchange status can change.
Towns Has a Product Before the Token Story
Towns is an open-source protocol for decentralized real-time messaging. Its technical overview describes an architecture built around Towns Chain, decentralized Stream Nodes, and smart contracts on Base. Users create programmable communities called Spaces with onchain memberships, access rules, encrypted group communication, and economic functions.
That architecture matters because Towns is not simply a social token attached to a chat application. Onchain contracts record memberships, Stream Nodes handle message propagation and synchronization, and smart contracts control parts of membership, rewards, governance, and protocol logic. The system therefore has a real service layer before the TOWNS value-capture question begins.
Project-reported dashboards have also shown substantial cumulative usage, including hundreds of thousands of Spaces and more than one million memberships. Those figures support the conclusion that the product has been used. They do not establish how many Spaces remain active, how many users pay repeatedly, or what share of historical activity produces protocol-controlled fees today.
That distinction is central. Usage and token demand can diverge when users can consume a product without continually acquiring the native asset. Towns needs a measurable route from communication activity into TOWNS buying, locking, or burning.
ETH Fees Give Towns a Real Value-Capture Route
Towns has a more credible starting point than projects that rely only on speculative token utility. Paid memberships, tips, and other transactions can generate ETH-denominated fees. The protocol’s pricing documentation explains how transaction economics flow to Space owners, the Towns ecosystem, and referrers.
This creates real economic activity, but revenue needs careful labeling. Money paid for a membership is not automatically protocol revenue. Creator earnings are not automatically treasury income. Gross transaction value is not automatically available for token buybacks. A useful token analysis therefore needs to follow the portion of fees that the protocol actually controls.
The intended value-capture route is buy-and-burn. The Towns token page says fees from memberships, tips, trading, and other transactions flow back into the ecosystem through automatic buy and burn mechanisms. The technical overview also says Towns can use collected ETH fees to repurchase and burn TOWNS.
If executed consistently, that mechanism can connect product usage to token demand. The protocol could use controlled ETH to buy TOWNS from the market and permanently remove the purchased tokens from supply. That is economically different from a reward system that simply pays users with newly issued tokens.
Where Fee Value Reaches TOWNS
The unresolved issue is scale. A buyback mechanism can exist while remaining too small to offset inflation. The key comparison is not whether any TOWNS has been burned. It is whether verified repurchases and burns are large enough relative to new issuance, vesting, treasury distribution, and selling by recipients.
The economic route also depends on fee ownership. A transaction can create real value for a Space owner while creating little value for TOWNS if most of the payment leaves the protocol. That is why a useful dashboard would show gross user spending beside the smaller amount retained by protocol-controlled addresses. Without that split, a large cumulative revenue number can look stronger for the token than the underlying cash flow actually is.
The direction of demand matters as well. A protocol-funded market purchase creates direct TOWNS demand. A user choosing to stake existing tokens creates a lock but not necessarily a new purchase. A reward paid in newly issued TOWNS increases supply. These flows can all happen at the same time, so the net result cannot be inferred from one metric alone.
Buyback Documentation Still Leaves a Proof Gap
Official Towns material does not describe the buyback process with fully consistent timing. The technical overview says collected ETH fees are used to periodically buy back and burn TOWNS. The current token page describes automatic buy and burn mechanisms. The pricing documentation, however, still refers to the buy-and-burn function as something to be implemented.
That wording conflict does not prove the mechanism is inactive. It does mean readers should not convert design language into a measured burn rate without transaction evidence. A strong public record would show the ETH assigned to repurchases, the TOWNS bought, the TOWNS burned, transaction dates, and net supply change over the same period.
Towns Lodge financial reporting provides useful context but not complete protocol accounting. Its Q2 2026 financial statement reported 3 billion TOWNS in the treasury as of June 30 and said no designated tokens were acquired or disposed of during the quarter. The report also states that it covers DUNA-controlled wallets and does not represent all financial activity across the wider protocol.
That limitation matters. The Lodge statement cannot prove that no buyback occurred through another protocol address. Readers also cannot use it as evidence that buybacks offset inflation. The central thesis remains plausible, but a cumulative burn ledger is still missing from the public evidence reviewed here.
| Evidence | Current Position | What It Proves |
|---|---|---|
| Paid memberships and tips | Fee-generating product activity exists | Users can create real economic activity |
| Project usage figures | Large cumulative adoption has been reported | Product usage exists, not current recurring demand |
| Buy-and-burn documentation | ETH fees have a stated route toward TOWNS | A value-capture design exists |
| Staking and delegation | TOWNS can be locked for network participation | Token utility exists, not net deflation |
| Towns Lodge Q2 report | Treasury held 3B TOWNS with no designated-token disposal in Q2 | Lodge treasury activity is partly transparent |
| Public burn evidence | Public materials provide no simple cumulative ledger | Net offset against inflation remains hard to verify |
Staking Locks TOWNS While Inflation Creates TOWNS
TOWNS is not limited to governance. Holders can delegate tokens to Node Operators, and Spaces can use delegated TOWNS to unlock protocol functions. Nodes need sufficient delegation to participate in the network. This gives the token a functional role that can remove some supply from immediate trading.
The reward side creates the opposite pressure. Towns economics documentation says annual inflation begins at 8 percent after year one and declines linearly over 20 years toward 2 percent. Governance can vote to lower the inflation rate, while Towns distributes rewards every two weeks to active Node Operators and their delegators.
Readers should not confuse a high staking yield with outside economic income. New issuance funds the reward system. The important test, similar to other inflation-funded staking models, is whether utility and fee-funded demand remain strong after the cost of emissions is included.
Public documentation also contains a withdrawal-rule conflict. The current staking utility page describes a 30-day cooling-off period that begins when unstaking starts. An older token-governance page describes a 60-day countdown after undelegation. The live contract and current interface should determine actual behavior, but Towns should reconcile the documentation because lock duration affects liquidity and user expectations.
Tokenomics: Inflation and Vesting Now Matter Together
Towns published a genesis supply of about 10.128 billion TOWNS. Its detailed allocation assigns 33.83 percent to the Community Reserve, 21.46 percent to the team, 14.98 percent to the initial airdrop, 13.74 percent to investors, 7.90 percent to Nodes Year 1, 4.2 percent to liquidity, 2.62 percent to public investors, and 1.27 percent to node inflation.
The first-year structure is no longer the whole story. TOWNS began trading in August 2025, and the documented inflation schedule starts after year one. Onchain supply evidence also shows that the token supply has moved above the original genesis figure. Etherscan has displayed roughly 10.77 billion TOWNS for the Ethereum contract, while market-data providers use different total-supply methodologies. The safest conclusion is that inflationary issuance is now economically relevant, not that every provider should show the same number.
Vesting creates a separate source of available supply. Towns documentation says the initial team and investor allocations have a one-year lock followed by two years of linear vesting. The one-year point has now passed. That does not mean vested tokens are automatically sold, but it does mean more tokens can become transferable over time.
This is where token unlock pressure needs precise language. An unlock changes availability. It does not prove an exchange deposit or sale. For TOWNS, the useful question is whether new transferable supply is met by enough recurring demand, delegation, and verified burning.
Current Supply Data Still Conflicts
Current circulating-supply estimates also disagree. As checked in September 2026, CoinMarketCap showed about 3.4 billion TOWNS circulating while CoinGecko showed about 2.109 billion. The lower CoinGecko figure matches the initial listing circulation closely, while Towns’ own published schedule projected roughly 3.672 billion at the 12-month point. That gap is large enough that readers should not treat one current circulating-supply figure as uncontested.
Supply reporting is especially difficult because TOWNS exists across more than one network and market trackers do not always use the same methodology for bridged balances, circulating allocations, and locked inventory. The Ethereum contract can show a different figure from an aggregator that attempts to reconcile balances across chains. That is a reason to qualify the numbers, not a reason to assume one provider is automatically wrong.
The primary schedule remains the better anchor for planned economics. It gives readers the original allocation percentages, a projected circulating path, and the inflation design. Market trackers are more useful for a current snapshot, but when their figures conflict with each other or with the published schedule, the disagreement itself becomes part of the analysis.
Maximum-supply language needs the same caution. The technical overview labels about 15.328 billion TOWNS as maximum supply after seven years. Other official economics material says inflation declines over 20 years until it reaches 2 percent. Those statements do not clearly establish that issuance permanently ends after year seven. Readers should therefore treat the 15.328 billion figure as a published seven-year supply projection unless Towns provides a clearer lifetime-cap explanation.
TOWNS Tokenomics
| Tokenomics Item | Current Position | Why It Matters |
|---|---|---|
| Genesis supply | About 10.128B TOWNS | Sets the original allocation base |
| Published T+84 supply | About 15.328B TOWNS | Shows major planned expansion over seven years |
| Inflation | Starts at 8% after year one | Creates new tokens for network rewards |
| Inflation path | Declines toward 2% over 20 years | Emissions slow but remain structurally important |
| Team allocation | 21.46% | One-year lock has passed into vesting period |
| Investor allocation | 13.74% | Adds another significant vesting stream |
| Community Reserve | 33.83% | Large pool can support future ecosystem distribution |
| Staking rewards | Inflation-funded and biweekly | Locking and new issuance occur together |
| Buy-and-burn | ETH fee-funded mechanism described by Towns | Needs transaction-level proof to measure offset |
| Circulating supply | Major provider disagreement | Current liquid supply requires qualification |
| Main tokenomics risk | Inflation and vesting exceed durable demand and verified burns | Product growth may not tighten token supply |
The model does not require TOWNS to become deflationary to have utility. It does require token demand to become meaningful relative to issuance. For emission-heavy infrastructure tokens, this balance often matters more than the headline staking yield.
Binance Monitoring Tag Is a Separate Risk Signal
Binance added TOWNS to its Monitoring Tag on September 4, 2026. According to the exchange, tagged assets carry higher volatility and risk than other listed tokens and face closer recurring review.
During these reviews, Binance considers development activity, trading volume, liquidity, network stability, smart contract stability, public communication, due diligence responsiveness, supply changes, tokenomics changes, and project conduct. The announcement did not identify which factor or combination of factors caused TOWNS to receive the tag.
Readers should not present the tag as proof that Binance objected to the 8 percent inflation rate, the vesting schedule, or the buyback mechanism. It also is not a delisting announcement. The relevant risk is that exchange access now carries more uncertainty if future reviews conclude that TOWNS no longer meets listing standards.
Governance Controls Part of the Supply Equation
TOWNS governance is economically relevant because delegated holders can influence protocol decisions and treasury use. Towns documentation says governance can lower the inflation rate but cannot raise it above the programmed path. That gives governance a direct lever over future emissions.
The treasury is also material. Towns Lodge reported 3 billion TOWNS in its treasury at the end of Q2 2026. Governance can direct treasury resources toward development and ecosystem programs. Those distributions may support adoption, but they can also move concentrated inventory into broader circulation.
Governance does not solve the buyback proof gap by itself. The stronger model would combine transparent fee accounting with clear proposals, identifiable buyback addresses, verifiable burns, and net issuance reporting. Readers could then separate governance intent from economic execution.
Treasury Concentration Still Matters
There is also a concentration question. A treasury holding of 3 billion TOWNS is large relative to current circulating-supply estimates. That does not mean the treasury will sell those tokens, and the Q2 statement reported no designated-token disposal during the quarter. It does mean governance decisions around grants, incentives, and ecosystem funding can materially affect future distribution.
A stronger governance framework would make those effects easy to follow. Proposal-level reporting can show why tokens move, who approved the use, what vesting or spending conditions apply, and whether the distribution supports activity that later produces protocol-controlled fees. Without that link, treasury spending may grow the ecosystem while still weakening token scarcity.
Security Depends on Contracts, Nodes, and Upgrade Control
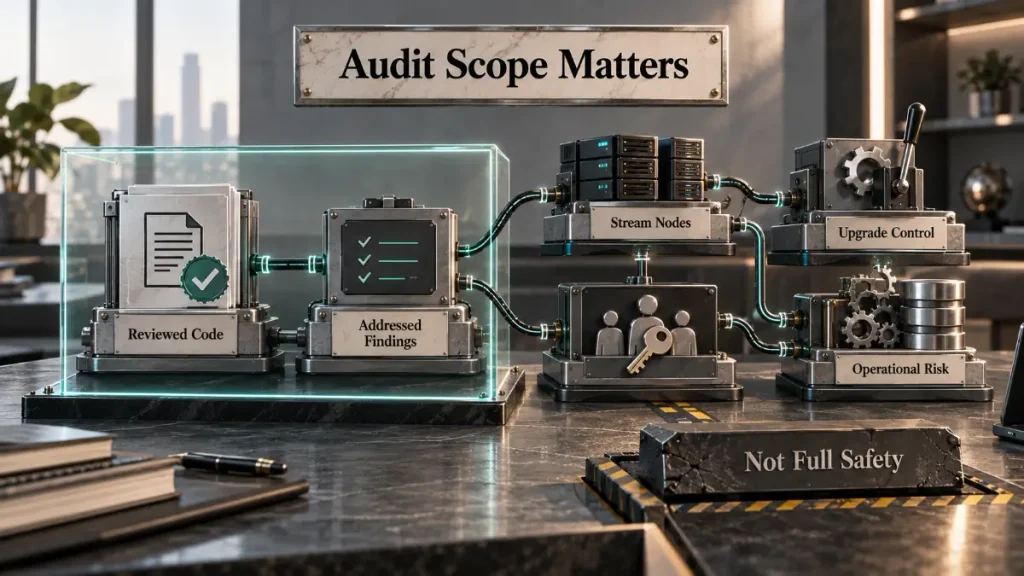
Towns has meaningful audit coverage, but its security model extends beyond one contract. Macro has reviewed multiple protocol components. Its October 2025 Subscription Module audit initially reported three high-severity and two medium-severity findings, including issues around renewals, charging, and user protections. Macro marks those findings as addressed in the reviewed code.
That remediation is positive evidence. It is not proof that the entire protocol is safe. Towns combines smart contracts, Stream Nodes, Towns Chain, Base contracts, encrypted messaging, token delegation, governance, and offchain infrastructure. Different components create different failure boundaries.
Upgradeability deserves particular attention. Towns uses the Diamond Pattern for modular smart contract upgrades. The Subscription Module audit notes privileged control over module logic and operator management, with multisig protection described as an important mitigation. Users therefore depend not only on deployed code but also on how upgrade authority and administrative keys are protected.
The distinction between audit and current security is important. An audit examines specified code at a specified point in time. It does not guarantee later upgrades, node operations, governance actions, or key management. A responsible review should therefore track both technical findings and who can change the system after an audit.
What Towns Needs to Prove Next
The first missing number is verified buyback scale. Towns needs a public record that links protocol-controlled ETH fees to TOWNS purchases and burns. Readers should be able to compare gross issuance, verified burns, and net supply change over the same period.
The second test is fee quality. Cumulative activity is useful, but recurring protocol-controlled fees matter more for value capture. Reporting should separate creator income, referrer payments, treasury receipts, protocol fees, and the amount actually assigned to token repurchases.
The third test is staking quality. Delegation is stronger when nodes and Spaces need TOWNS for useful network functions. Demand driven mainly by inflationary rewards is less convincing because the network pays for that demand with new tokens. Readers should therefore track delegated supply, reward rates, and organic utility together.
The fourth test is documentation consistency. Towns should reconcile the 30-day and 60-day withdrawal descriptions, clarify whether the 15.328 billion figure is a seven-year projection or permanent cap, and provide one current description of buy-and-burn execution. These are not cosmetic details. They affect how holders evaluate liquidity, dilution, and value capture.
Towns Protocol Review Verdict: Revenue Ahead of Burn Proof
Towns has a stronger foundation than a token built around a future product. It has decentralized messaging infrastructure, programmable Spaces, paid memberships, network delegation, governance, and a route for ETH-denominated activity to support TOWNS demand.
The unresolved economic issue sits between fee generation and verified token capture. Inflation is now relevant while team and investor vesting can increase transferable supply. Staking can lock tokens, but inflation funds the rewards. Buy-and-burn could counter part of that pressure, yet the public evidence still lacks a simple cumulative record that lets readers compare repurchases and burns directly with new issuance.
The Binance Monitoring Tag increases the importance of transparency without explaining the cause. Readers should treat it as a separate exchange risk, not evidence that one specific tokenomics mechanism has failed.
TOWNS therefore has a credible product and a plausible value-capture route, but the central result remains unproven. The strongest evidence would be recurring protocol fees, identifiable TOWNS purchases, verifiable burns, transparent net issuance, and durable delegation moving in the same direction.
Frequently Asked Questions
Towns Protocol is open-source infrastructure for decentralized real-time messaging. It combines programmable Spaces, onchain memberships, encrypted communication, decentralized Stream Nodes, Towns Chain, and smart contracts on Base.
TOWNS supports node delegation, Space-level utility, governance, and network rewards. Nodes need sufficient delegation to participate, while delegated tokens can also unlock additional functionality for Spaces.
Towns uses inflation to fund rewards for Node Operators and delegators. Official economics documentation says the rate begins at 8 percent after year one and declines linearly over 20 years toward 2 percent.
Towns describes a fee-funded buy-and-burn mechanism in official materials. The main evidence gap is not whether the mechanism is described. It is the lack of one simple public ledger that shows cumulative TOWNS repurchases and burns against gross issuance.
The technical overview presents roughly 15.328 billion as maximum supply after seven years. Other official material describes inflation declining over 20 years toward 2 percent. Until Towns reconciles those statements, the figure is safer to treat as a published seven-year projection rather than an unquestionable lifetime cap.
No. The tag means Binance considers the asset subject to higher risk and closer review. Binance can later remove the tag or delist TOWNS if future reviews find that the token no longer meets listing standards. The September 2026 action itself was not a delisting announcement.
Yes. Macro has reviewed several Towns components, including token, staking, rewards, and subscription-related contracts. Audit scope varies by component, and an audit does not prove that the full protocol, future upgrades, or operational controls are secure.

Founder & Managing Editor of CryptosMedia. Zahid Hussain leads evidence-based crypto research covering tokenomics, security, governance, adoption, and risk.
CryptosMedia separates verified facts from interpretation, avoids buy/sell recommendations, and updates reviews when major evidence changes.